Explore potential truck leasing scenarios with our Truck Lease Calculator. Adjust lease amounts, residual (balloon) payments and repayment terms to estimate costs and see how different finance assumptions may influence your business repayments and cash flow.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual costs and repayments may differ.
Truck Lease Details:
Important!
Truck Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Truck Lease Amortisation Calculator
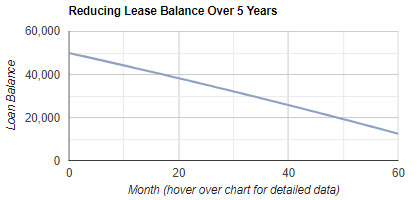
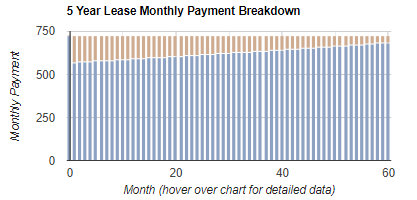
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Truck Lease Finance Repayment Calculator
Our Truck Lease Finance Repayment Calculator helps Australian businesses estimate truck lease repayments before speaking with a lender. By modelling purchase price, interest rate, term and a residual or balloon payment, you can compare options, stress-test cash flow, and choose a structure that suits your operational needs and end-of-term plans (keep, refinance, trade, or pay out).
Why it matters: Truck lease repayments can look affordable while still carrying a large end payment. Adding a residual or balloon value may reduce monthly repayments, but it can increase total interest and leave a sizeable amount due at the end of the term. The calculator makes that trade-off clear.
How to complete the form for the best result
1. Purchase Price: Enter the truck’s purchase price as a whole number (no decimals, commas or symbols). Where relevant, consider whether you want to include on-road and other costs such as stamp duty, registration, insurance and tax-related amounts in your finance estimate (only include costs you expect to fund).
2. Balloon or Residual Value: Choose the residual as a percentage of the purchase price. A higher percentage generally lowers ongoing repayments but increases what you will owe at the end of the lease. Select a level that matches your expected end-of-term strategy and business cash reserves.
3. Term of Loan: Select the number of years you want to repay over. Longer terms typically reduce periodic repayments but can increase the total cost over time.
4. Interest Rate: Select an annual interest rate for the simulation. The listed rates are indicative only; your actual rate may differ based on lender policy and your circumstances. .
5. Calculate: Click calculate to generate the estimate and charts.
How to interpret the results
Review the estimated repayment amount alongside the amortisation charts showing the reducing balance over time and the split between interest and principal across the term. Use these outputs to compare scenarios, for example changing residual percentage or term, and to plan for the end-of-term residual payment.
ASIC compliance and important notes: This calculator provides general information and estimates only. It does not consider your objectives, financial situation or needs and is not financial or credit advice. Results may exclude fees, lender charges, taxes and timing assumptions. Consider seeking professional advice and obtaining a formal quote before making a decision.
If you're running a business in Australia, trucks might be a crucial component of your operations. Whether for transportation, delivery, or service, trucks play a vital role in ensuring business efficiency and success. However, acquiring these vehicles is not always straightforward, leading many business owners to face the lease vs buy dilemma. Understanding the right financing option for trucks can significantly impact your business's financial health. - read more
Personal truck finance can help an individual buy a truck for private or mixed personal use, but it is assessed differently from business truck finance. This guide explains common loan structures, eligibility factors, costs, documents and how personal truck loans differ from commercial options. - read more
When it comes to managing a fleet, the financial decisions you make can significantly influence your business operations. Understanding the impact of fleet costs is crucial, as it helps in ensuring the sustainability and efficiency of your operations. High fleet costs can eat into your profits, making it vital to find cost-effective solutions. - read more
For many businesses across Australia, trucks are not just vehicles—they're an integral part of operations. Whether it's delivering goods, providing services, or transporting raw materials, having a reliable truck can make all the difference in ensuring smooth business operations. - read more
A recent Money magazine examination of a no-deposit home loan model has put an important lending issue back in front of Australian borrowers: a smaller upfront cash hurdle does not automatically mean a lower-risk loan. The discussion centred on Zeroo, a product model that says it can finance the full purchase price of a property, with the borrower contributing settlement-related costs and the provider exiting later through refinancing once sufficient equity has built up. - read more
Fresh October 2026 credit-demand data from Equifax, reported on 18 November 2026, suggests Australian households are becoming more cautious about large long-term borrowing while still leaning on shorter-term credit to manage everyday pressure. Mortgage demand fell sharply over the year, while credit card and personal loan demand moved higher, a split that says a lot about affordability, confidence and cash flow. - read more
The Reserve Bank of Australia’s latest board minutes have added important context to the 3 November increase in the cash rate, showing a central bank divided not over whether inflation matters, but over how much more pressure the economy can absorb. The board ultimately lifted the cash rate target by 25 basis points to 4.85%, with six members voting for the move and three preferring to hold at 4.60%. - read more
Fresh Australian Bureau of Statistics lending figures have highlighted a sharp reset in the housing finance market, with investor borrowing falling much faster than owner-occupier lending in the September quarter of 2026. For first home buyers, that may sound like a welcome shift after years of competing with cashed-up investors, but the same data also shows that getting into the market is still far from straightforward. - read more
Debt Consolidation: Taking advantage of lower interest rates that may be available by the grouping of multiple loans into one, lower interest rate loan.